Key takeaways
- Comps are recently sold properties similar to your subject in location, size, condition, and features, and they form the backbone of any CMA.
- Pull three to six closed sales from the last 90 days within a quarter mile or the same subdivision, then adjust each one rather than averaging.
- Adjust each comp so it resembles the subject: subtract value when the comp is superior and add value when it is inferior.
- Keep gross adjustments under roughly 10% of a comp's sale price; a comp needing more is probably not a true comparable.
- Present comps to sellers by leading with their net number and walking through the adjusted math so the gap is arithmetic, not opinion.
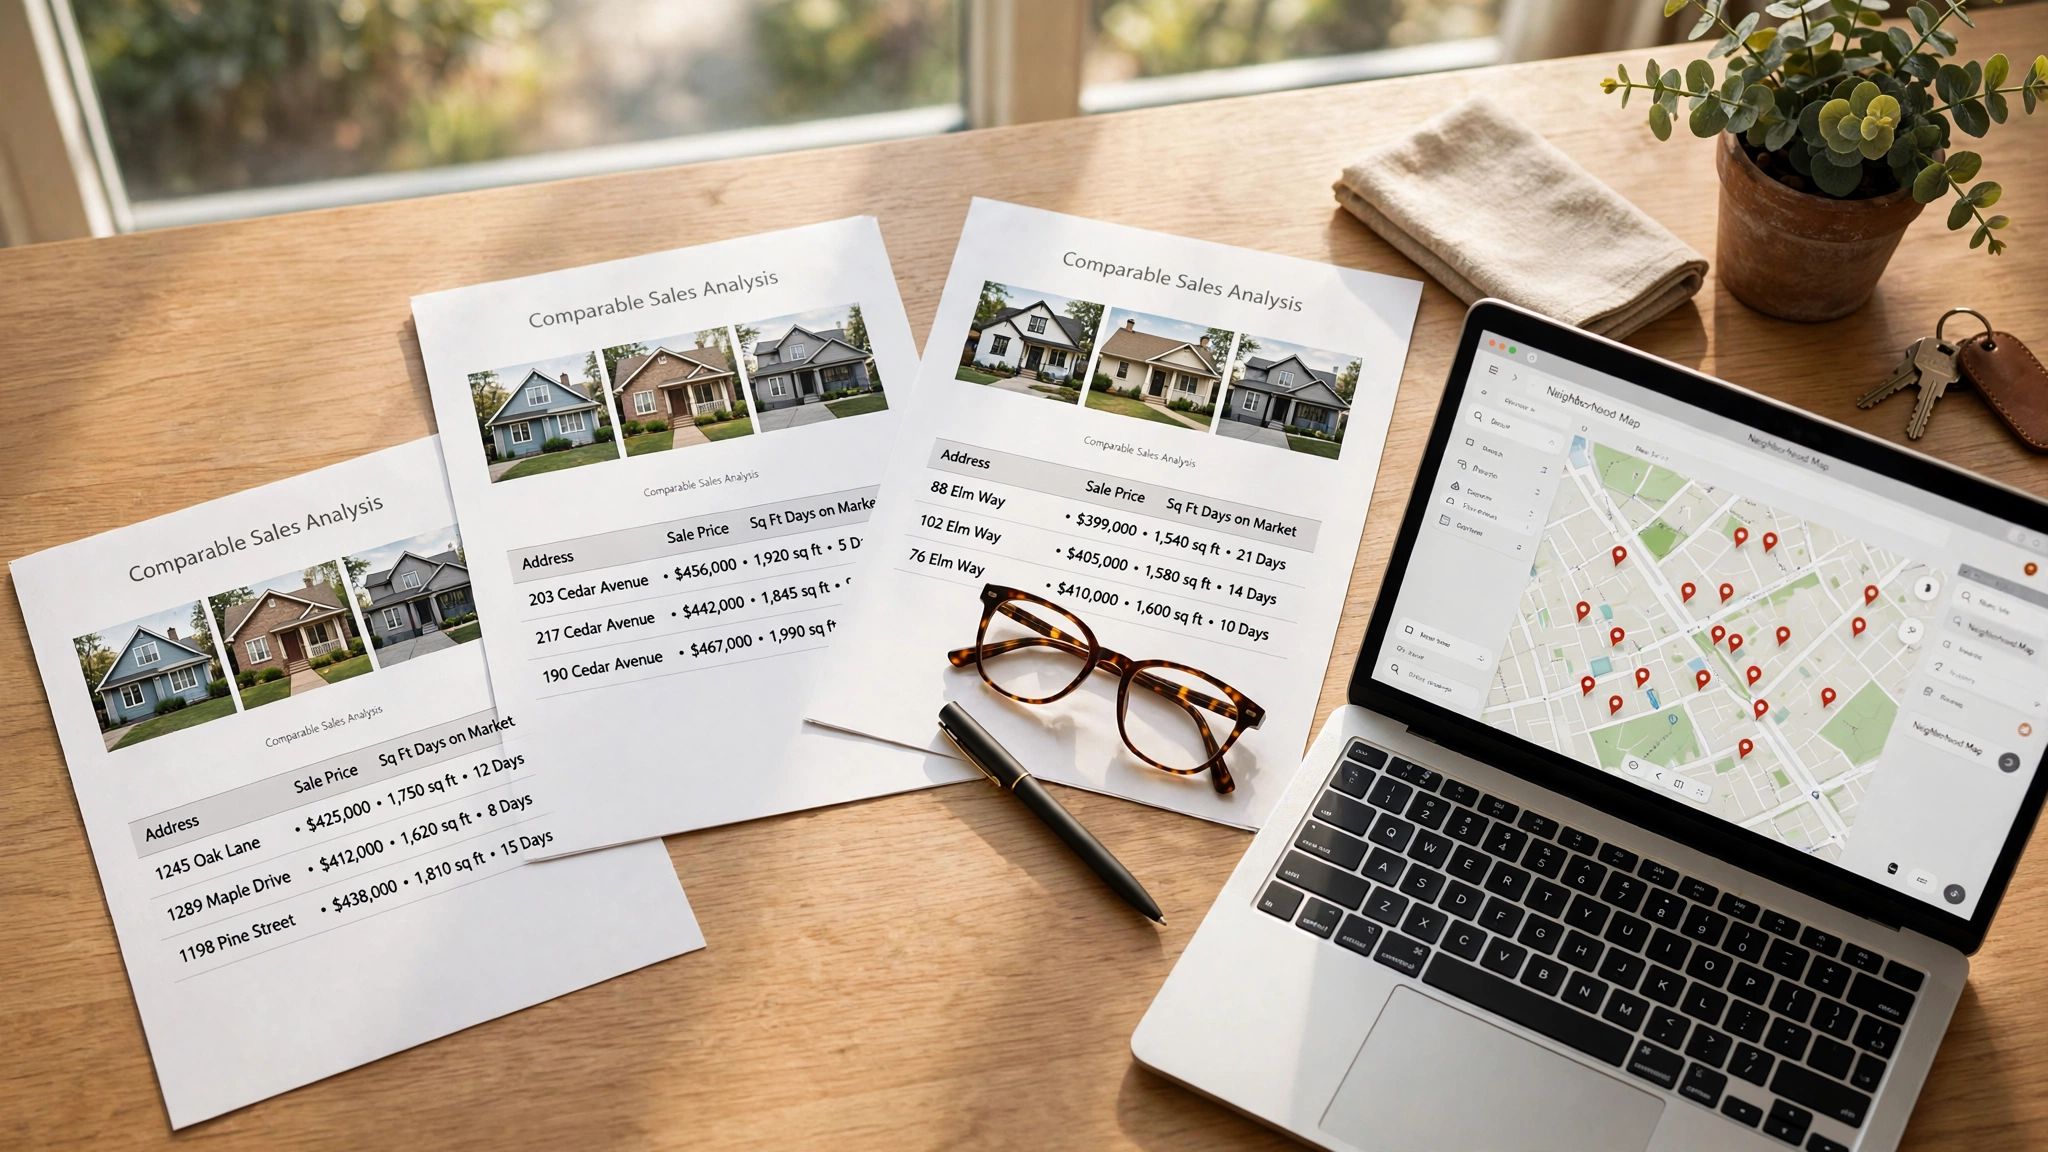
Comps in real estate are recently sold properties similar to your subject property in location, size, condition, and features, and they are the backbone of any CMA you run before setting a list price. You pull three to six of them from the MLS, adjust each sale price for differences like square footage or a garage, and reconcile the adjusted values into a defensible price range for your seller.
What is the comps definition in real estate?
Comps (comparables) are recently sold properties similar to yours in location, size, condition, and features. Agents use them to estimate what a listing will sell for before setting a price or building a CMA. A comp is a closed sale, not an asking price, so the data reflects what buyers actually paid.
Comps for real estate vs. an appraisal
A CMA is an agent's estimate built from comps; an appraisal is a licensed appraiser's formal opinion, often required by a lender. NAR explains the distinction and why agents must not present a CMA as an appraisal: CMA vs. appraisal. If you want help pulling comps and turning them into a seller-ready report, our tools handle both.
How do you do comps for real estate step by step?
A workable comps process is six steps: pull solds, filter to true matches, adjust, reconcile, then price. Here is the version you can run on any listing.
Step 1: Define the search area and timeframe
Start with solds from the last 90 days within a quarter mile, or the same subdivision. Rural or slow markets may need six months. Widen only if you find fewer than three usable sales.
Step 2: Filter by property basics
Match beds, baths, square footage within about 15 to 20 percent, lot size, garage, and condition. Skip foreclosures and distressed sales unless your subject is one. Three to six solid comps beat ten shaky ones.
Step 3: Adjust, don't just average
Adjust each comp so it resembles your subject: if a comp has a garage and yours does not, adjust the comp's price down. Sales of the subject's features come from paired sales or cost estimates, not guesses. This is the step most agents skip, and it is where a credible CMA is won. Once adjustments are in, a tool like our offer comparison sheet keeps the math straight when a seller is weighing multiple offers against your suggested list price.
Step 4: Reconcile and price
Weight the adjusted comps by similarity, land on a tight range, and pick a list price with your seller's net sheet in front of you.
How do you determine which properties qualify as good comps?
Run every candidate through a checklist before it earns a spot in your CMA. Fannie Mae's appraisal guidance expects comparable sales that are recent, nearby, and similar enough that adjustments stay reasonable (Fannie Mae Selling Guide).
The 10-point comp selection checklist
- Sold within the last 3–6 months (up to 12 in a slow market)
- Within a half mile in a city, or the same subdivision in suburbs
- Same bed and bath count, or within one
- Similar square footage, ideally within 20%
- Same property type and style
- Similar lot size
- Same condition tier: updated, original, or fixer
- Not a foreclosure or short sale unless the seller's situation matches
- Closed, not pending or active
- Arm's-length sale between unrelated parties
Score each candidate honestly. A comp that fails two or three points still works if adjustments are small and defensible; one that fails five is a stale listing or a flip, and it will skew your seller's net sheet. When your photo set is thin, staged shots from Agent Copilot AI's virtual staging help your listing compete with comps that show better than it does.
What adjustments should you make when comparing comps?
Adjustments correct for differences between each comp and your subject property: size, age, condition, lot, garage, and features like pools or finished basements. The rule is simple: if the comp is superior, subtract value; if the comp is inferior, add value. You are asking what the comp would have sold for if it were identical to your subject.
Worked example: adjusting three comps to one subject property
Say your subject is a 1,800 sq ft, 3-bed/2-bath ranch built in 2005 with no pool. You have three closed sales nearby:
- Comp A: 1,950 sq ft, with a pool. Sold for $415,000. Adjustments: −$9,000 for size, −$10,000 for the pool. Adjusted value: $396,000.
- Comp B: 1,750 sq ft, built in 1985. Sold for $389,000. Adjustments: +$4,000 for size, +$12,000 for age. Adjusted value: $405,000.
- Comp C: 1,800 sq ft, with an updated kitchen. Sold for $405,000. Adjustment: −$8,000 for condition. Adjusted value: $397,000.
The adjusted values cluster around $396,000–$405,000, so you land on a likely list range of about $400,000–$410,000, weighted toward Comp B since it needed the fewest total dollars of adjustment.
Where adjustment values come from
Adjustment figures come from paired sales (two similar homes differing in one feature), local appraisal rules of thumb, or your MLS closed data. The dollar amounts in the example above are illustrative, not market data. If you want help turning raw comps into listing copy and a seller's net sheet, see our roundup of AI tools for real estate agents.
How do commercial real estate comps differ from residential comps?
What changes for commercial real estate comps?
Residential comps lean on the sales comparison approach: similar sold homes, adjusted for differences. Commercial comps shift toward the income approach, where value tracks the rent a tenant pays. You compare price per square foot, cap rates, lease terms, and tenant quality instead of bedroom counts.
Leases complicate everything. A 10,000 square foot office with ten years left at $30/sq ft is not comparable to one with 18 months remaining, even on the same block.
Freddie Mac's appraisal guidance spells out what lenders expect from comps: same market area, recent sale window, and gross adjustments generally capped around 10%, and commercial underwriting applies similar discipline to income data.
A commercial comp selection checklist
- Same property type and similar size band
- Sale within the last 6-12 months, same submarket
- Verified rent roll, not asking rents
- Lease expirations and tenant credit noted
- Cap rate computed from actual net operating income
If you work both sides, keep the processes separate. Your residential CMA habits will mislead you on a strip mall, and Agent Copilot AI's updates at https://agentcopilotai.com/updates track what our tools cover today.
What is the best website for real estate comps?
For most solo agents, the honest answer is your MLS. It has the freshest sold data, the most accurate square footage, and the status history public sites guess at. Its weakness is that pulling a clean CMA still means exporting, formatting, and writing it up yourself.
Free public sites are fine for a quick gut check, but their estimates lag the market and mix in non-arms-length sales. Paid tools add polish and speed, though many charge per feature or push you toward virtual staging add-ons you may not need.
Comparing comp sources side by side
MLS wins on data quality. Public sites win on price. Paid tools win on presentation, and that is where Agent Copilot AI fits: it does not replace your MLS data, it turns the comps you already pulled into adjusted values, a listing description, and a client-ready report in minutes, for a flat $29/month.
Where it falls short: it is not a data source, so you still need MLS access, and it is residential-focused rather than a commercial comps tool.
Can a real estate comps calculator replace manual comps?
No. A calculator or AI tool can pull recent sales, suggest adjustments, and draft the CMA in minutes, but it cannot stand in a kitchen and know the seller gutted it two years ago or that the next street over carries freeway noise. Commercial data providers like CoStar publish detailed comps and cap rate methodology precisely because the data needs a trained eye on top of it. The same holds residential: software speeds the math, you supply the judgment.
Where Agent Copilot AI fits, and where it falls short
Agent Copilot AI builds the CMA skeleton, drafts the listing description, and generates a seller's net sheet from your inputs, which is most of the busywork for $29/month flat. Where it falls short: it will not verify a comp's condition from a photo, catch an unpermitted addition, or weigh a stale listing's psychology. Run your own comps through it, then adjust by hand before the listing appointment.
How do you present comps to sellers without losing the listing?
Lead with the seller's number, not yours. Ask what they hope to net, then show the adjusted comps and the seller's net sheet side by side so the gap is math, not opinion.
Walk through three comps out loud: sale price, adjustments, and why each one qualifies. Sellers who see your reasoning trust the number, even when it is lower than Zillow said.
If the price is still too far apart, offer a staged test: strong photos, virtual staging or day to dusk edits, a tight listing description, and a scheduled price review after two weeks. A stale listing costs more than an honest starting price.
FAQ
How many comps do you need for a CMA?
Three to six solid comps is the working target. Three is the minimum for a defensible range, and more than six usually means padding with weak matches instead of adjusting the strong ones. If you cannot find three within your initial search area, widen the radius or timeframe until you can.
Do comps have to be in the same subdivision?
Not strictly. The same subdivision is ideal in suburbs, but a quarter to half mile radius works in cities. What matters is that comps share the same market forces: school zone, buyer pool, and neighborhood character. A comp across a major road or district line can mislead even if it looks identical.
How old can a comp be before it stops counting?
Aim for sales from the last 90 days. In a normal market, anything past six months drifts from current buyer behavior, and 12 months is the practical ceiling even in slow or rural areas. If you must reach back that far, adjust for market movement, not just property differences, and say so in your CMA.
What is the 10% rule for comps?
It is a lender expectation, drawn from appraisal guidance, that gross adjustments on a comparable sale generally stay under about 10% of the sale price. If you need to adjust a comp by more than that, it is probably not a true comparable. Freddie Mac's underwriting guidance applies similar discipline to commercial income data.
Are Zillow estimates the same as comps?
No. A Zestimate is an automated model estimate; a comp is a closed sale you select and adjust by hand. Public site estimates lag the market and can mix in non-arms-length sales, which skews the number. Use them for a quick gut check, but build the CMA from MLS solds you have verified yourself.